Completing the 2009 non dom pages
Firstly, there is the main tax return itself (www.hmrc.gov.uk/forms/sa100.pdf)
Secondly there is the residence and remittance basis supplementary pages (www.hmrc.gov.uk/forms/sa109.pdf)
Thirdly, there are the foreign supplementary pages (www.hmrc.gov.uk/forms/sa106.pdf), and
Finally, there are the capital gains supplementary pages (www.hmrc.gov.uk/forms/sa108.pdf)
The main tax return
Completing the main tax return to reflect your non dom status is actually pretty straightforward. However the special pages of the tax return for non doms usually only need completing if you're using the remittance basis.
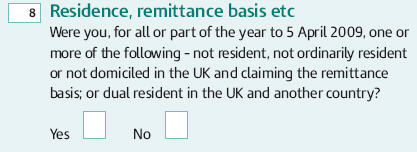
You would need to tick 'Yes' to box 8 on page TR2 if you were using the remittance basis in the tax year. So even if you had overseas unremitted income or gains of less than £2,000 you would still need to tick 'Yes' to this.
If you weren't using the remittance basis then you would tick 'No' and usually wouldn't need to provide any specific disclosures in terms of your non dom status. This would not prevent you from claiming the remittance basis in future years.
 |

|
The residence and remittance pages
As above, when completing these pages it's only if you're using the remittance basis that you'll usually actually have to complete the form.
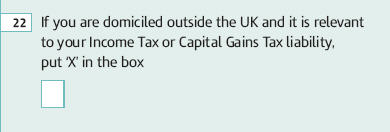
It starts off by asking if domicile is relevant to your income tax or CGT liability:
 |
|
This would only usually be the case if you were a UK resident, but non UK domiciled, you had overseas unremitted income or gains and wished to use the remittance basis. It would therefore need to be ticked even if you had under £2,000 of overseas unremitted income or gains.
If, however, you were a non dom but had no overseas unremitted income or gains or just wanted to claim the arising basis you would not tick box 22, and would then leave the other boxes blank as well. You'd then be taxed on the arising basis and would enter all your UK and overseas income and gain on the tax return.
If you were using the remittance basis you would tick box 22 and also complete boxes 23-26 as appropriate (these ask for details as to the date you became non UK domiciled).
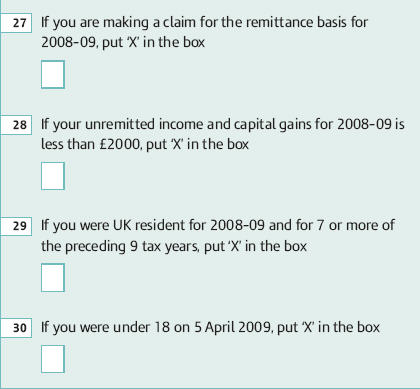
You'd then need to actually claim the remittance basis on the tax return in box 27.
 |
|
Box 29 will be ticked if you've been UK resident for 7 or more of the 9 previous tax years. In that case you would then be liable to the £30,000 remittance tax charge unless you were under 18. You would need to tick box 30 if you were aged under 18.
If you were liable to pay the £30,000 remittance tax charge there are also a number of additional boxes that you would need to complete:
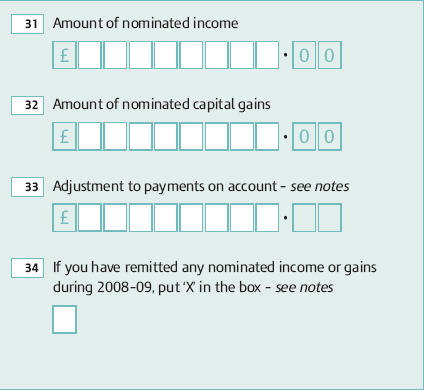 |
|
By claiming the remittance basis you would then only enter details of overseas income or capital gains actually remitted into the UK on your UK tax return.
As such, if you retained all your overseas income or gains abroad you would not provide details of these income/gains on your tax return.
If you did remit overseas income or gains you'd need to complete:
You'd enter remittances from both the current year and any previous years in these pages as well.
Related Articles
Selling property in Portugal & reducing UK tax
· Overseas redundancy payment and UK income tax
· How to avoid the anti avoidance rules that catch non doms remitting income whilst non resident
· Traders moving overseas and NIC
· Non dom and tax on a gift from overseas family?
· Non Dom with offshore company paying UK rent?
· Dividends and the remittance basis of tax
· Transfer of land to a company
· 50% Income Tax From 2010
· Non Dom remittance dividend tax rates